

CONTRIBUTORS

Jackie Cavanaugh
Portfolio Manager, Analyst

Will Rives, CFA
Portfolio Manager, Analyst
Attention Is Concentrated. Strength Isn’t.
Investor attention is concentrated in one place: artificial intelligence (AI). The 10 largest constituents of the S&P 500 Index, many of them tied to the AI buildout, now make up roughly 39% of the index.1 In Bank of America’s October survey of global fund managers, semiconductors were named the most crowded trade. A net 37% of respondents were overweight technology, the most since August 2020.2 When attention is this concentrated, strong businesses elsewhere can be overlooked. Our portfolio managers follow the fundamentals, not the crowd.
Here, two of them make their case: Jackie Cavanaugh sees a consumer that is strong but under-owned, and Will Rives sees medical devices that are still growing but trade at a discount to the rest of health care. The sectors differ, but the pattern is the same.
Consumer Strength Beyond the AI Trade
Jackie Cavanaugh
Jackie covers the financials, real estate and consumer sectors. She joined Putnam in 2011 and has worked in the investment industry since 1995.
The consumer is strong. Yet far fewer investors are positioned for it, as attention and capital keep chasing the AI story. In the same Bank of America survey noted above, a net 34% of managers were underweight consumer discretionary, the largest underweight since 2008.2
In recent corporate management meetings, the feedback on consumer health was uniformly positive. Consumer spending continues to rise across categories, with September card spending per household up 6.2% (5.1% excluding gas) year-over-year based on Bank of America Institute data.3 While higher gas prices account for some of that uplift, they're not the sole driver. We are seeing broad-based strength in cruises, movies, quick-service restaurants and clothing spend. Nearly 86% of discretionary retail categories saw spending growth in September, the broadest reading in more than five years.3
There is more holding this market up than the AI wave alone.”
Wage growth hasn't fully caught up to inflation, but the gap is closing, and job changers are seeing meaningful wage gains of roughly 12.5%, the highest in more than three years,4 underscoring continued demand for labor. Credit trends remain excellent, as the share of credit card accounts paid in full matches its record high and charge-offs at the largest banks fall year-over-year.5 This resilience isn't confined to higher earners. Lower-income households are now seeing the fastest after-tax wage growth of any group: 4.5% year-over-year in September, versus 3.8% for middle-income households and 3.7% for higher-income households.6 Loan demand from small- and medium-sized businesses is notable, and it signals confidence to borrow and invest in growth.
Taken together, these trends point to a healthier, broader economic backdrop than the AI-driven narrative alone would suggest. For us as investors, it reinforces the case for individual, fundamental stockpicking over simply riding the AI wave. There's more supporting this market than one theme, and that breadth matters for how we position portfolios.
Jackie’s case rests on demand that is broad and resilient. Will sees a similar setup in health care, where demand holds up in any environment, but one corner of the sector has been left behind.
What Health Care’s Rally Left Behind
Will Rives, CFA
Will covers the health care, energy, materials, utilities and industrials sectors. He joined Putnam in 2013 and has worked in the investment industry since 2013.
Health care has had two very different years. Over the last 12 months, pharmaceuticals are up about 41% while medical devices are down about 14%.7 Same sector, opposite results, and the gap has pushed device stocks to their cheapest level against the rest of health care in 20 years.
Pharmaceuticals have had the better of it. After dealing with tariff and drug pricing challenges, the industry seems to have come to a détente on the policy front, and innovation has refocused attention on solid fundamentals.
Things are very different in the less-discussed medical device area of health care. Here, companies like Medtronic, Stryker or Boston Scientific make the physical devices used in health care, from surgical equipment to heart valves to hip and knee implants. After a strong post-COVID period driven by pent-up health care needs and a broad innovation cycle, growth has moderated, making 2026 a challenging year. The discount reflects growth returning to normal after the post-COVID surge, disappointments at a few large names that weighed on the whole group, and money moving to other parts of the market. Figure 1 shows how much cheaper device stocks have become compared with the rest of health care. For every $1 investors pay for a dollar of health care earnings, they now pay about 97 cents for a dollar of device earnings, compared with about $1.30 on average over the past 20 years.
Figure 1: Medical Device P/E Relative to Health Care
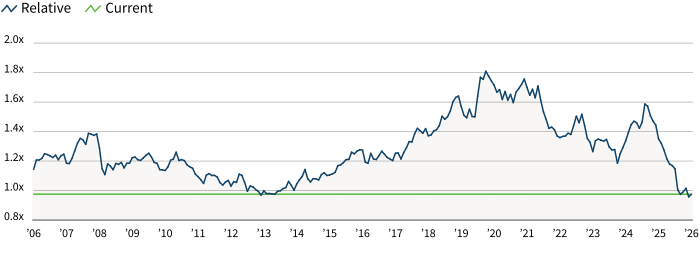
Source: Bloomberg. Medical devices: S&P 500 Health Care Equipment Index. Health care: S&P 500 Health Care Index. Trailing price-to-earnings (P/E) ratio, weekly, October 20, 2006—October 13, 2026. A reading of 1.0x means medical device stocks trade in line with health care.
Despite the pessimism, we are encouraged by the opportunities ahead. Growth has moderated, but from elevated levels back to “normal” in our view. Industry growth in the mid-single digits or better is durable and should continue to lift earnings per share over time. We see several exciting innovation cycles continuing, including robot-assisted surgery and less invasive treatments for heart valve disease.
Unfortunately, disease burden doesn’t slow down over time. Health care is one of the areas where demand is consistent regardless of the macroeconomic situation. The market has cooled on medical-device stocks, but we see opportunity in stocks with durable growth that we believe are poised for brighter days ahead.
Growth in medical devices has slowed to a normal pace, but the stocks are priced as if something is broken.”
Opportunities Beyond the Market Leaders
Both views point to the same conclusion: concentrated investor attention can obscure strength elsewhere. Consumer businesses are healthy but under-owned. Medical device companies are growing steadily yet valued as though they are not.
These opportunities do not depend on the AI trade reversing. The 10 largest constituents of the S&P 500 make up roughly 39% of the index, illustrating where investor attention is concentrated, not necessarily where fundamentals are strongest.
Our research points to consumer businesses with underappreciated resilience and medical-device companies with durable growth that current positioning and valuations may not fully reflect. We see both as compelling areas for disciplined stock selection.
Endnotes
-
Source: S&P Dow Jones Indices, “S&P 500 Factsheet.” As of September 30, 2026. The 10 largest constituents represented 39.1% of the index by weight. Alphabet’s Class A and Class C shares are listed separately.
-
Source: Bank of America Global Research, “Global Fund Manager Survey,” October 2026. Survey conducted October 2–8, 2026, with 161 respondents managing $453 billion.
-
Source: Bank of America Institute, Daily Insights, October 9 and October 12, 2026. As of September 2026.
-
Source: Bank of America Institute, “The Institute Employment Report: August 2026,” September 3, 2026. Median pay change associated with a job-to-job change, three-month moving average, as of July 2026 (12.5%).
-
Source: Federal Reserve Bank of Philadelphia, “Large Bank Credit Card and Mortgage Data: 2026 Q2 Insights Report,” October 7, 2026 (share of accounts making a full payment and net charge-off rates); JPMorganChase and Capital One, third quarter 2026 earnings releases, October 2026.
-
Source: Bank of America Institute, Daily Insights, “Lower-income wage growth cooled, but remains ahead,” October 7, 2026. After-tax wage and salary growth by household income tercile, three-month moving average, year-over-year, seasonally adjusted, as of September 2026.
-
Source: Dow Jones. Pharmaceuticals: Dow Jones U.S. Select Pharmaceuticals Index. Medical devices: Dow Jones U.S. Select Medical Equipment Index. Total returns for the one-year period ended September 30, 2026. Index returns are for illustrative purposes only. Index performance returns do not reflect any management fees, transaction costs or expenses. Indexes are unmanaged and one cannot invest directly in an index. Past performance does not guarantee future results.
WHAT ARE THE RISKS?
All investments involve risks, including possible loss of principal. Past performance is not an indicator or a guarantee of future performance.
Active management does not ensure gains or protect against market declines.
Equity securities are subject to price fluctuation and possible loss of principal.
The investment style may become out of favor, which may have a negative impact on performance.
Large-capitalization companies may fall out of favor with investors based on market and economic conditions.
Focusing investments in the health care, information technology (IT) and/or technology-related industries carries much greater risks of adverse developments and price movements in such industries than a strategy that invests in a wider variety of industries.
Any companies and/or case studies referenced herein are used solely for illustrative purposes; any investment may or may not be currently held by any portfolio advised by Franklin Templeton. The information provided is not a recommendation or individual investment advice for any particular security, strategy, or investment product and is not an indication of the trading intent of any Franklin Templeton managed portfolio.
Price-to-earnings (P/E) ratio is a valuation measure that divides a stock’s or index’s price by its earnings per share. A trailing P/E uses reported earnings for the past 12 months. A relative P/E divides one P/E ratio by another.